ASELSAN:
 Lockheed Martin:
 Rheinmetall:
 BAE Systems:
 Thales:
 Leonardo:
 Saab:
 Kongsberg Gruppen:
 Indra Sistemas:
 Mitsubishi Heavy Ind.:
 Hanwha Aerospace:
 AVIC Shenyang Aircraft:
 Hindustan Aeronautics:


KEY INTELLIGENCE TAKEAWAYS & SUMMARY
- While venture capital directed to defense technologies has increased 10-fold since 2019, the market value of global aerospace and defense companies reached 1.6 trillion dollars.
- There is a serious capital shortage and supply bottleneck in gallium, germanium, solid fuel rocket motors (SRM), energetics and special casting parts.
- Second and third tier (Tier-2/3) underwing stores do not increase defense capabilities due to high acquisition costs and the profitability of the civil sector.
- It is necessary for states to make direct equity investments in strategic areas and to develop new incentive models to attract private capital to high-risk infrastructure projects.
<h2>Critical components and funding gap in the lower load layer</h2>
The amount of private capital flowing into the defense technologies ecosystem has expanded tremendously in recent years, reaching record levels. While venture capital investments in the sector increased approximately tenfold compared to five years ago, the total market value of global aerospace and defense giants exceeded the 1.6 trillion dollar mark. However, this abundance of capital in financial markets is not evenly distributed among the most critical and fragile points of the military production line. While capital mostly flows into upper-layer technologies such as software, artificial intelligence and autonomous systems with high profitability and fast return; The physical manufacturing infrastructure that forms the backbone of the industrial base is experiencing a severe drought.
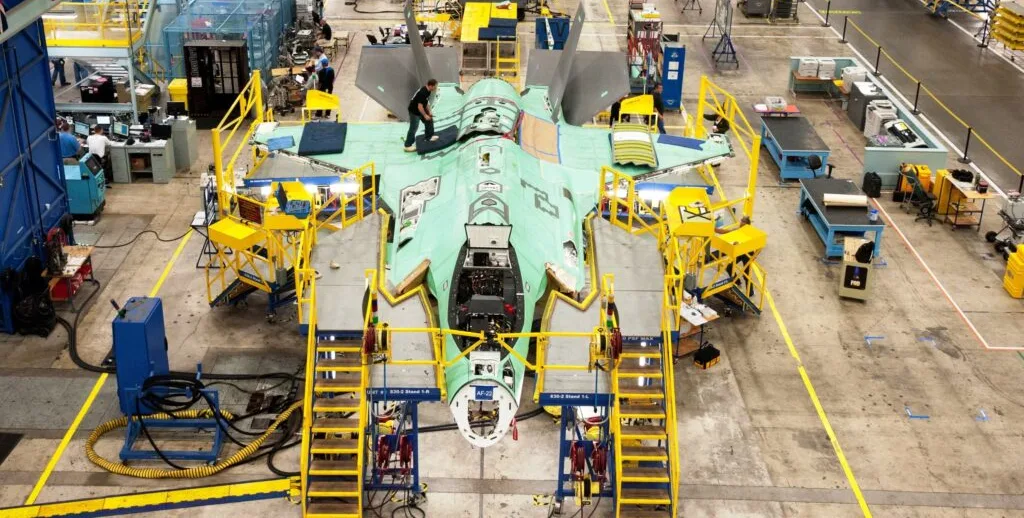
There are huge supply gaps, especially in the processing of critical minerals such as gallium and germanium, which are vital in a wide range of military applications, from missile systems to radar systems and advanced magnets. However, capital flows in strategic subsystems such as solid fuel rocket engines (SRM), casting and forging components, explosive raw materials (energetics) and advanced semiconductors have come to a halt. Second and third tier (Tier-2 and Tier-3) subcontractors have difficulty attracting the attention of private equity funds due to high capital requirements, sharp fluctuations in global commodity prices and long investment processes. Many smaller manufacturers are choosing to shift their limited capacity to commercial and civilian sector contracts that offer higher profit margins, rather than defense projects.
Sponsor AdPromote Your Defense Brand Globally Across 6 Languages
Reach military procurement officers, defense contractors, and AI (GEO/AEO) search engines in 6 languages.
<h2>State Intervention and Private Capital Mobilization</h2>
<h2>Result and Future Perspective</h2>
<p>Future high-intensity conflict scenarios and geopolitical crises compel the defense industry not only to have innovative software but also to possess a resilient physical infrastructure that operates continuously. Insufficiency of resources at the component level creates a "single point of failure" risk in the supply chain, directly threatening operational readiness levels for global-scale operations.</p>
In the coming period, mixed financing models in which state-supported incentives and direct public investments are integrated with private capital will play a critical role. Unless artificial steps are taken to modernize the manufacturing capacities of second- and third-tier suppliers, eliminate dependence on critical raw materials, and secure mass production of strategic components such as solid-fuel rocket engines, financial growth in the defense sector will not translate into a tactical production superiority in the field.